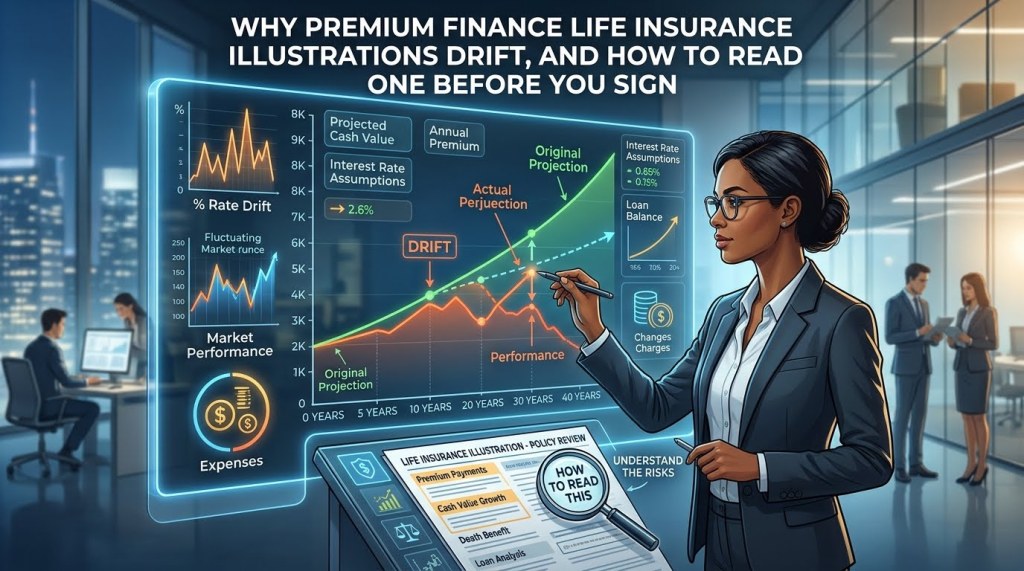


Anyone who has compared a life insurance illustration printed at issue with the policy’s actual values fifteen years later knows the two rarely match. That gap is not necessarily a sign that something went wrong. It is built into how illustrations work. In a premium-financed policy, though, the gap matters more, because a loan, interest costs, and collateral requirements all depend on how the policy performs.
This article explains what an illustration actually shows, which variables drive drift over time, and how to read the document so you can spot potential problems before signing rather than after.
What an Illustration Is, and What It Is Not
Premium finance life insurance pairs a permanent life insurance policy with a third-party loan that pays the premiums. The policy is illustrated under insurance regulations. The loan is governed by a separate agreement with the lender.
Under the NAIC’s life insurance illustration model regulation, an illustration is a depiction of policy values over time that includes non-guaranteed elements. Guaranteed elements are premiums, benefits, values, credits, or charges determined at issue. Non-guaranteed elements are everything else.
The regulation also requires a disclosure that says, in substance, that the illustration assumes current non-guaranteed elements will stay the same for every year shown, that this is not likely to occur, and that actual results may be more or less favorable. That sentence is printed on the document for a reason. An illustration is a comparison tool, not a forecast.
Two Systems Moving at Once
A financed policy depends on two independent systems.
- The policy involves crediting, mortality charges, expense charges, surrender charges, and the funding pattern.
- The loan involves a benchmark rate, a lender spread, reset provisions, interest payments, collateral requirements, and renewal.
The illustration describes the first system. The loan agreement describes the second. Nothing forces them to move together. Credits can come in lower in the same year that borrowing costs reset higher. A review that looks only at the illustration has examined half the structure.
The calendars also differ. A policy may be illustrated to age 100, while premium finance loans are commonly structured with terms of one to five years that require a new lender decision at each renewal.
Read the Columns in the Right Order
Most presentations lead with the current illustrated values. A more useful approach reverses that order:
- Guaranteed column first. This is the contractual floor and the only part of the ledger that cannot change.
- Reduced non-guaranteed basis second. This NAIC-defined view cuts illustrated dividends in half and moves credited rates and charges toward guaranteed levels. Because charges move too, a design that is sensitive to rising policy charges will show it here.
- Alternate scale third, for indexed policies. Actuarial Guideline 49-A requires an alternate-scale ledger that generally lowers indexed crediting by 100 basis points from the illustrated maximum, shown with equal prominence for affected policies sold on or after April 1, 2026.
- Current illustrated column last.
The numeric summary page is the fastest place to compare. It shows values at policy years five, ten, and twenty, and at age seventy where applicable, across guaranteed, illustrated, and reduced bases. That one grid tells you how much of the design’s apparent strength depends on favorable assumptions.
Watch the Years Where Premiums Change
The detailed ledger must flag every year in which the premium outlay changes. Find those years. A ledger that shows premiums stopping in year eight is not showing a paid-up policy. It is showing an assumption that policy values will cover ongoing charges from that point forward. The NAIC model requires a disclosure that charges continue and that premiums may need to resume depending on actual results.
Ask what the plan is if the assumption behind each change does not hold.
Separate Account Value From Surrender Value
Account value and net surrender value are different numbers. Net surrender value is what remains after surrender charges, policy loans, and policy loan interest are deducted. Surrender charge periods on some policies can extend beyond a decade.
In a financed arrangement, this distinction is not a footnote. If the lender measures collateral using net surrender value, anything that reduces crediting or increases charges tightens your collateral position directly.
Loan Interest and Time Compound Together
Premium finance loans typically carry variable rates tied to benchmarks such as Prime or SOFR, and lenders generally require periodic interest payments throughout the term. That is a recurring obligation regardless of what the policy credits in a given year.
Reinsurance underwriting guidance has identified loan interest paid at least annually, rather than accrued, as a characteristic of a more durable design, along with additional collateral beyond the policy itself. Accrued interest compounds against the same collateral the lender is measuring.
Renewal is a separate risk. Lenders have stated publicly that renewal is not guaranteed, and that a decline in collateral value may require the borrower to post more collateral or reduce the loan balance. Requalification at an older age can involve both financial and medical considerations. Lenders also generally require an identified repayment source that is not the policy’s death benefit, so a clear repayment plan belongs in the file from the start.
Build a Review Cadence for Both Systems
Monitoring tools already exist. After the first policy anniversary, you can request an in-force illustration based on current assumptions. Annual reports for universal life policies show beginning and ending values, credits and charges by type, net surrender value, and loans. The breakdown of credits and charges is exactly what you need to diagnose drift.
The same reporting framework includes two early warnings: a notice if guaranteed assumptions would not keep coverage in force through the next reporting period without more premium, and a notice of adverse changes to non-guaranteed elements. Treat both as signals, not routine mail.
On the loan side, track interest dates, rate resets, collateral reports, and the next maturity date. Once a year, compare the policy report, the in-force illustration, the current loan terms, and the collateral position against the original assumptions, and document what changed.
The Bottom Line
The most valuable part of an illustration is not its final-year number. It is the regulated disclosure of which assumptions the policy depends on and where they are allowed to change. Read the columns in the right order, read the loan agreement with equal care, and set a review cadence that covers both systems. That habit is what separates monitoring an arrangement from simply hoping it holds.
This article is for general educational purposes only and does not constitute legal, tax, or investment advice. Life insurance is not a security or investment product. Premium finance involves borrowing from a third-party lender. Interest-rate risk, lender risk, and policy-performance risk are all present. Values shown in any illustration are non-guaranteed projections based on current assumptions; actual results will vary. Past performance is not indicative of future results. NAIC model regulations are not automatically adopted in every state; confirm the rules that apply where you live. Not suitable for all clients. Consult your legal, tax, and financial advisors.



Leave a Reply